Compare Live Mortgage & Home Equity Rates
Compare current APRs, points, fees, and estimated monthly payments from participating lenders below.
Mortgage rates
Late payments don’t have to be the end of your refinancing journey. Let’s tackle this together and help you take back control of your finances!
FHA Guidelines to Beat Late Payments
Quick Answer: Yes, you can refinance an FHA loan after late payments, but eligibility depends on the severity and recency. For an FHA Streamline refinance, you typically need no more than one 30-day late payment in the last 12 months and no 60+ day lates. Standard FHA refinances allow more flexibility with a letter of explanation and improved payment history.
Mortgage Payment History: Unlock Your Eligibility
FHA lenders examine payment history like detectives! Here's how:Last 12 Months
- Best Position: 0 late payments – Gold standard!
- May Qualify: 1 late (30 days), but FHA refinance after late payments can be challenging.
- Difficult Approval: 2+ late payments
Last 24 Months
- Optimal: No late payments 60+ days
- Explanation Required: 1 late (60 days)
- Significant Hurdle: 90+ days late
Other Account Late Payments (Credit Cards, Loans, etc.)
- Weighted less heavily than your mortgage.
- Still matters, but lenders zoom in on your mortgage first!
Streamline vs. Standard FHA Refinancing
FHA Streamline Refinance: The QUICK Path After Late Payments
If you’re already an FHA borrower, this might be your ticket!Here’s How You Qualify:
- No more than 1 x 30-day late (past 12 months).
- ZERO 60+ day late payments (past 12 months).
Pro Tip: Streamline underwriting is laser-focused on RECENT performance, not ancient history. If you’ve had late payments, this is your chance to shine!
Standard FHA Refinance: For More Complex Cases
More scrutiny = higher barriers. Here's what to prepare:- Full credit analysis
- Income proof
- Explanation Letters (Explain the "why" behind late payments).
How to Qualify Even with Late Payments
1 Write a Winning Letter of Explanation (LOE)
Spill the REAL story behind your late payments, especially if you’re considering an FHA refinance after late payments.Make It Powerful:
- What happened? (“Unexpected job loss left me scrambling…”)
- Why it WON’T happen again? (“I’ve regained stable employment & started a savings cushion.”)
- How you’re a stronger borrower today?
Common Excuses Lenders Understand:
- Medical emergencies
- Job loss
- Natural disasters
- Divorce complications
- Identity theft
2 Show Your Financial Comeback Story
Lenders LOVE proof of improvement:- 12+ months PERFECT on-time payments.
- Current on all debts .
- A rock-solid income that feels bulletproof.
3 Build Bulletproof Strength
Offset weaker payment history by:- Cash Reserves (3-6 months of payments).
- Debt-to-income perfection.
- Healthy Home Equity .
- Durable, stable employment history.
Lender Insights
Choose the Right Partner
Late payments make lender choice CRUCIAL, especially when considering an FHA refinance after late payments.More Tolerant Lenders:
- FHA-focused specialists
- Portfolio lenders
- Credit unions
- Big banks
- Select online lenders
Waiting Period: How Long Until You’re Ready?
| Payment Type | Suggested Wait Period |
|---|---|
| 30-day late | 6-12 months perfect payments |
| 60-day late | 12-18 months stability |
| 90+ day late | 18-24 months improvement |
Use the Wait Wisdom
- Build perfect payment history.
- Slay your debts.
- Stockpile emergency reserves.
- Gather airtight documentation !
YouTube Video Learning Center
Let visual explanations guide your journey:How FHA Streamline Refinancing Works
Video Embed:Late Payments & Mortgage Refinancing Explained
Video Embed:Special Situations
COVID Forbearance
- Didn’t harm your payment history–great news!
- Show proof you exited successfully .
- Provide forbearance agreement if asked.
Divorce Drama
- Document it all: divorce decree + improved post-split finances!
Medical Hardships
- Story + medical proof = sympathy for lates (but your comeback MATTERS most).
Bookmark this guide–it’s packed with power moves for your FHA journey, especially if you're looking to FHA refinance after late payments!
Frequently Asked Questions
How many late payments are allowed for an FHA Streamline refinance?
For an FHA Streamline refinance, you generally can have no more than one 30-day late payment in the past 12 months and no 60-day or more late payments in that same period. Lenders may have overlays, so check with your lender.
What is a letter of explanation for FHA refinance after late payments?
A letter of explanation is a written statement detailing why your late payments occurred, such as job loss or medical emergency, and explaining how your financial situation has improved. It helps lenders understand the circumstances and assess your current ability to repay.
Can I refinance an FHA loan with a 580 credit score after late payments?
Yes, FHA loans allow credit scores as low as 580 with a 10% down payment, but refinancing after late payments may require a higher score or compensating factors like stable income, cash reserves, and a strong letter of explanation. Lenders vary in their requirements.
Expert Tip
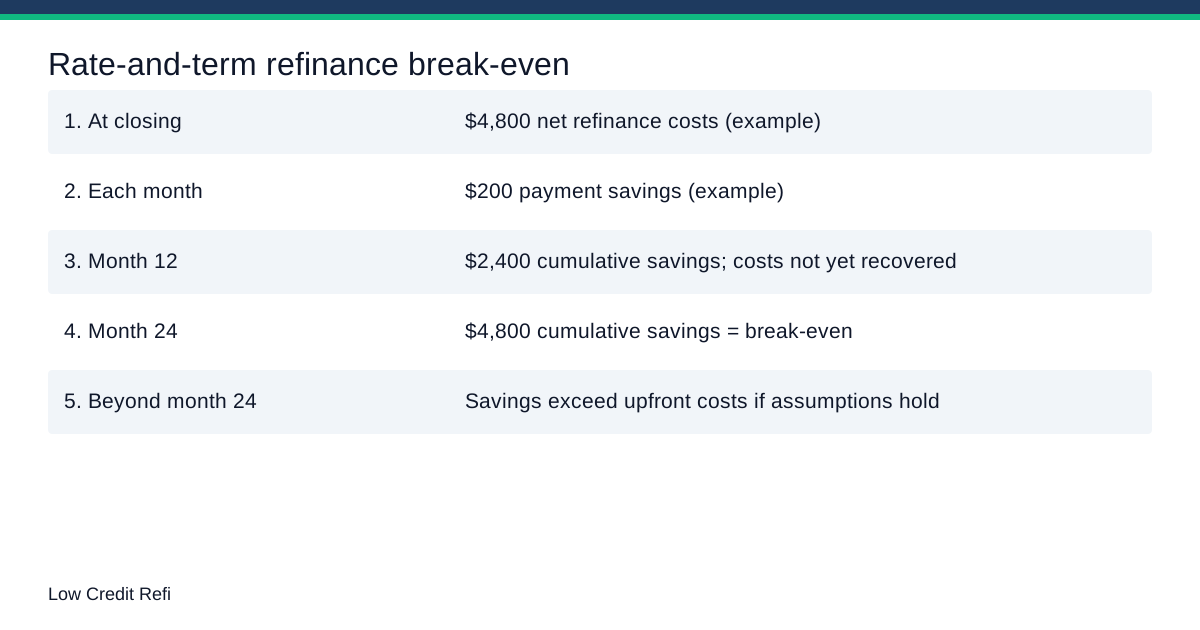
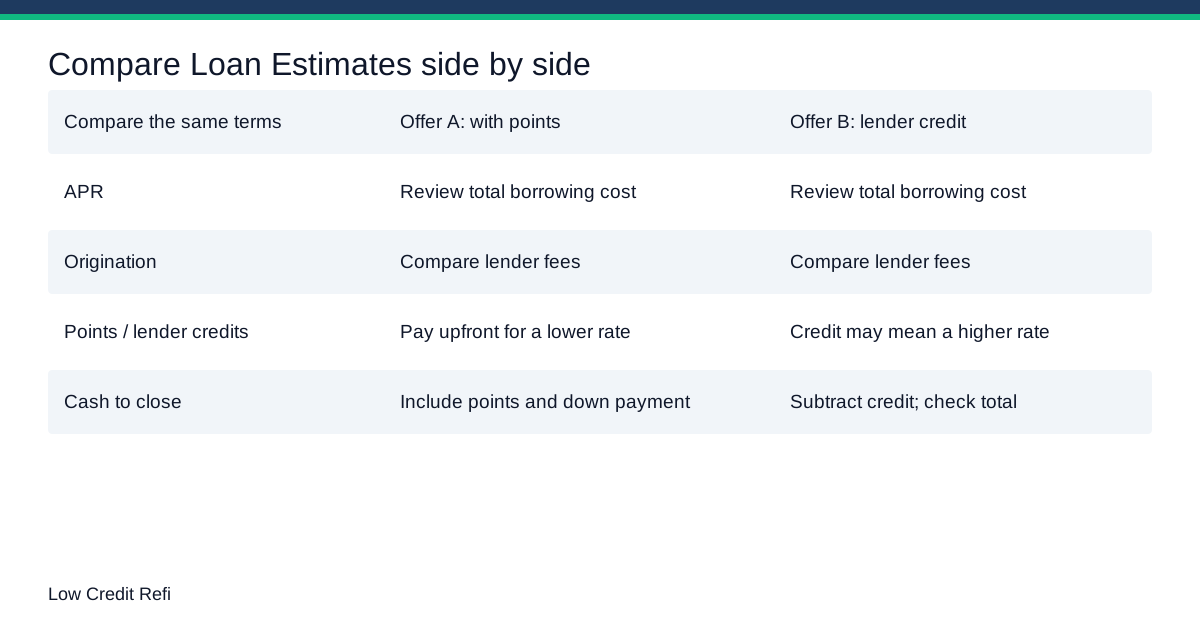
Compare Loan Estimates for the same loan type and term. Include closing costs when calculating whether refinancing saves money.
How long do I have to wait after a 30-day late payment to refinance FHA?
There is no set waiting period for a single 30-day late payment, but most lenders prefer to see at least 6 to 12 months of on-time payments after the late payment to demonstrate improved payment behavior. For a Streamline refinance, you must have no more than one 30-day late in the last 12 months.
Key Takeaways
- Understanding your options for fha refinance after late payments is the first step
- Explore related options like late payments fha loan
- Explore related options like refinance with late mortgage payments
- Getting pre-qualified helps you understand your real options

