Compare Live Mortgage & Home Equity Rates
Compare current APRs, points, fees, and estimated monthly payments from participating lenders below.
Mortgage rates
Refinancing With a 600 Credit Score: The Door to a Better Mortgage Opens Here
A 600 credit score might feel like a hurdle, but here’s the truth: it’s your stepping stone to a better financial future. With options like FHA, VA, and even certain conventional loans, you’re closer than you think to transforming your mortgage—and your life. If you're considering how to refinance 600 credit score, let’s dive in!
Your Refinancing Options: Pick the Perfect Fit
FHA Refinancing: The Flexible Choice for 600 Scores
FHA loans are designed to help borrowers with less-than-perfect credit scores, making them a top option for refinancing with a 600 credit score. Here’s how they work:
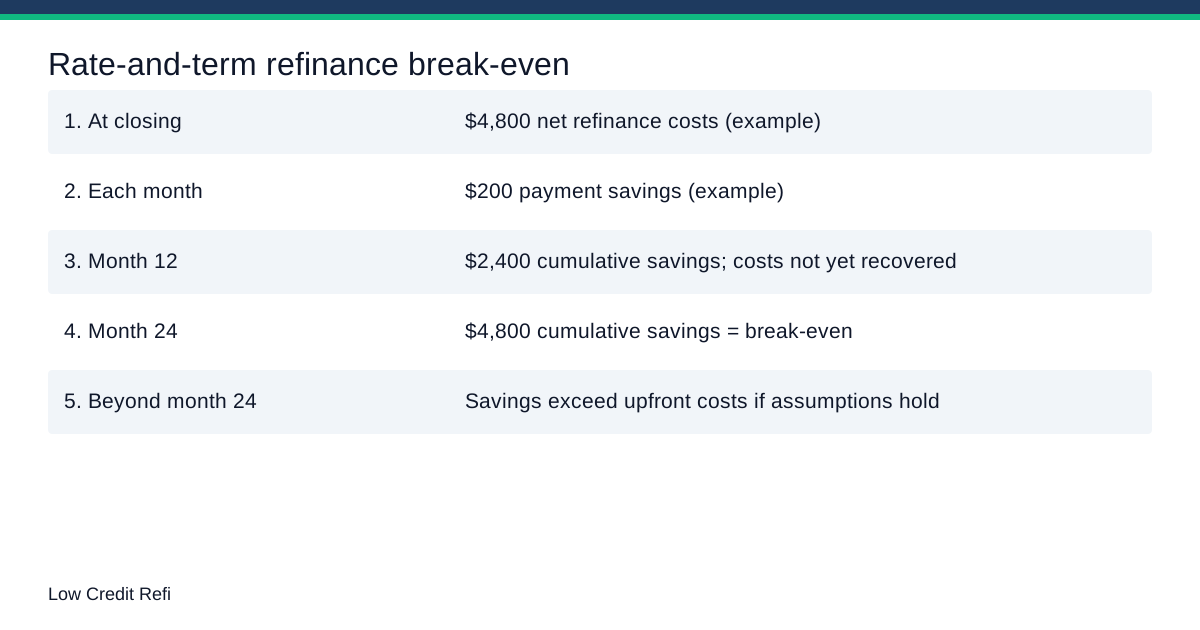
Rate-and-Term Refinance:
- Lower your interest rate, even with a 600 score.
- Shift from a 30-year term to a faster 15-year plan to save thousands in interest over time.
- Enjoy the stability of fixed rates over unpredictable adjustable ones.
- Minimal paperwork and hassle-free processing.
- Skip the appraisal process, speeding up approval and saving money on upfront costs.
- Lower closing costs, making it easier to refinance without breaking the bank.
- Access up to 80% of your home’s equity to fund home improvements, pay off high-interest debt, or finance major life goals.
- You must own your home for at least 12 months to qualify—but the payoff can be worth the wait.
VA Refinancing: Exclusive Perks for Veterans
If you’ve served in the military, a 600 credit score won’t hold you back from accessing the unique benefits of VA loans. These refinancing options are tailored to help veterans, active-duty service members, and eligible spouses.
IRRRL Refinance (Streamline):
- Quick and easy processing with minimal credit requirements.
- Skip the appraisal process, saving time and avoiding unnecessary fees.
- Access the full equity in your home, unlike other loan programs.
- No monthly mortgage insurance, reducing your monthly payment burden.
Watch This Video:
Conventional Refinancing: High Equity Could Give You A Leg Up
This is especially relevant for those interested in 600 credit score mortgage refinance.
Conventional loans are less forgiving when it comes to credit scores, but they can still be an option for borrowers with a 600 score under certain circumstances.
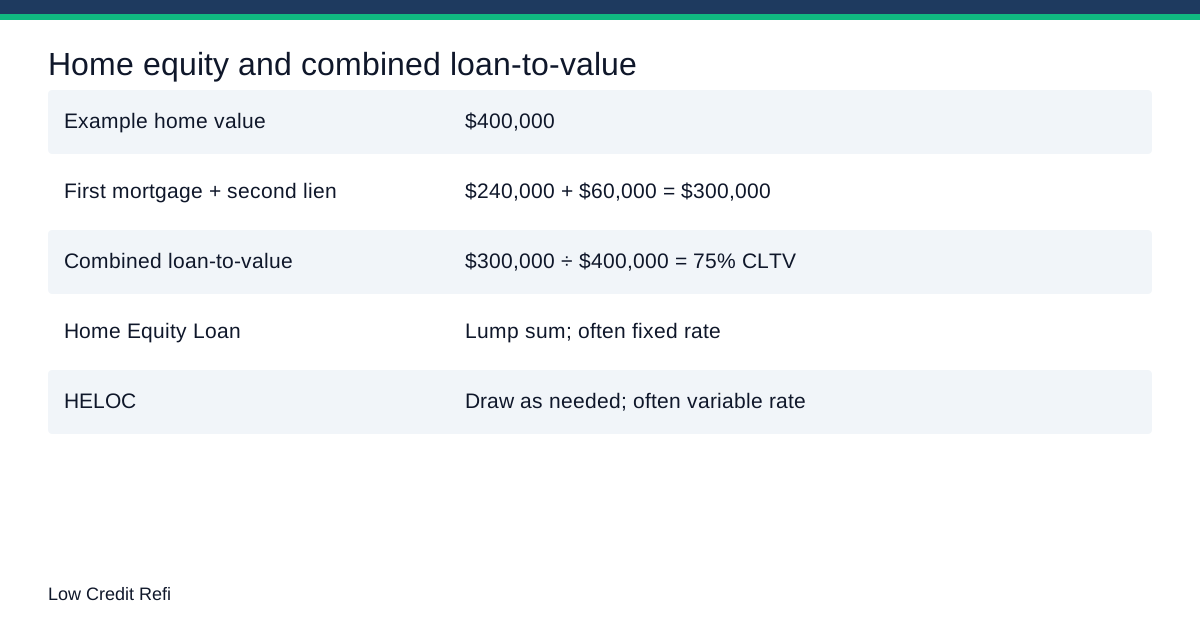
- If you have 25% or more equity, some portfolio lenders may approve your application.
- Expect slightly higher interest rates compared to FHA and VA loans.
- This option is best for homeowners looking to avoid lifetime FHA mortgage insurance costs or who want more flexibility in loan terms.
What Refinancing Rates Can You Expect?
Wondering what your refinancing rates might look like with a 600 credit score? Although rates vary based on market conditions, here’s a snapshot of what you can expect:
| Loan Program | Estimated Rate Premium |
|---|---|
| FHA Loans | Market + 0.25% to 0.50% |
| VA Loans | Market + 0.125% to 0.375% |
| Conventional Loans | Market + 0.75% to 1.25% |
Example: If the current market rate is 6.50%, a borrower with a 600 credit score might see these rates:
- FHA: 6.875% - 7.000%
- VA: 6.625% - 6.875%
- Conventional: 7.25% - 7.750%
Steps to Optimize Your 600 Score Refinancing Journey
Expert Tip
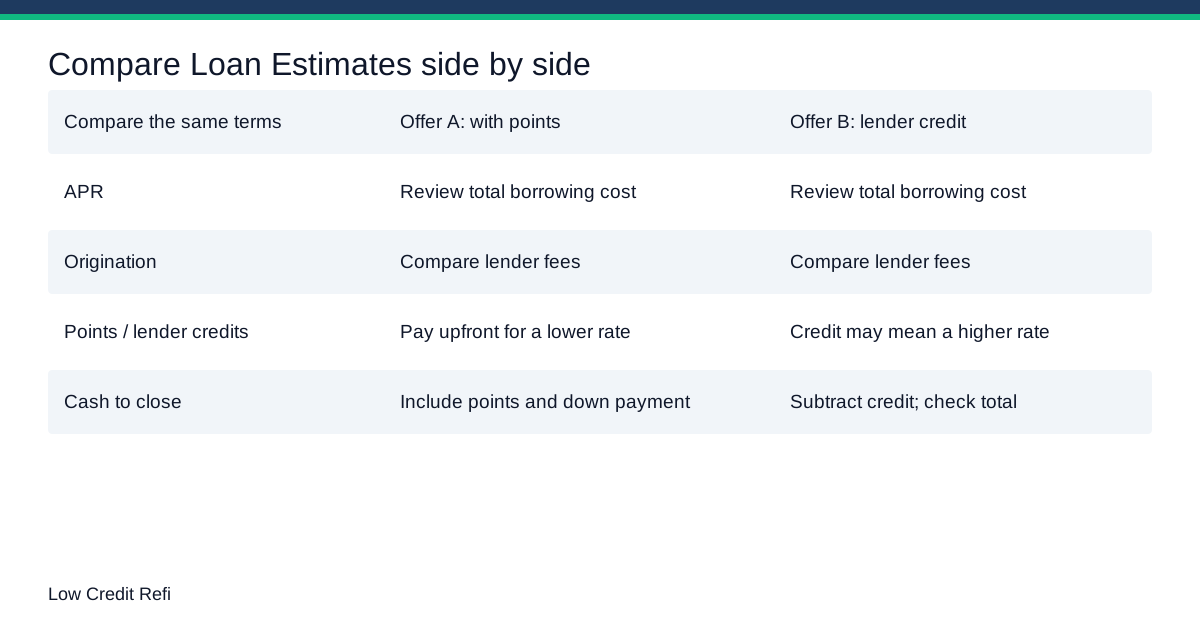
Compare Loan Estimates for the same loan type and term. Include closing costs when calculating whether refinancing saves money.
Preparation is key to successful refinancing, especially with a 600 credit score. Follow this checklist to ensure you’re ready to impress lenders:
Essential Documents Checklist:
- Tax Returns: Provide your last two years of filings.
- W-2s: Submit income statements for the past two years.
- Pay Stubs: Show at least 30 days of recent income proof.
- Bank Statements: Provide at least two months of account history.
- Mortgage Statement: Include details of your current loan.
- Insurance Policy Declarations: Show proof of coverage on your property.
Avoid These Common Mistakes:
- Opening New Credit Accounts: Resist the urge to apply for new credit cards or loans before refinancing.
- Making Large Purchases: Overspending on big-ticket items can hurt your debt-to-income ratio.
- Switching Jobs: Stability matters to lenders, so avoid changing employment during the refinance process.
- Unnecessary Financial Transfers: Keep your accounts organized and consistent to avoid raising red flags.
Boost Your Credit from 600 to 620 for Big Savings
While refinancing is possible with a 600 credit score, increasing your score to 620 can unlock better rates and more loan options. Here’s how to do it:
Benefits of a 620 Credit Score:
- Access lower interest rates, saving thousands over the life of your loan.
- Qualify for more loan programs, including better conventional options.
Actionable Tips to Improve Your Credit:
- Pay down existing debt to lower your credit utilization ratio.
- Set up automatic payments to ensure timely bill payments.
- Avoid hard inquiries by refraining from applying for new credit accounts.
- Check your credit report for errors and dispute inaccuracies.
Your Next Step in Refinancing
A 600 credit score doesn’t have to limit your refinancing potential. With the right preparation, you can reduce your interest rates, access your home equity, and improve your financial outlook. Start by exploring FHA, VA, and conventional loan options, gather your documents, and take actionable steps to boost your credit score.
You’ve Got This! Refinancing with a 600 credit score is your opportunity to take control, save money, and create a brighter financial future. Don’t wait—start your journey today by considering how to refinance 600 credit score effectively!
Key Takeaways
- Understanding your options for refinance 600 credit score is the first step
- Explore related options like 600 credit score mortgage refinance
- Explore related options like 600 fico refinance rates
- Getting pre-qualified helps you understand your real options

